“Money is a terrible master but an excellent servant.” – P.T. Barnum
Introduction: The Scary Truth About the American Dream
Let me ask you a question.
If you lost your job today, how many months could you survive without borrowing money?
- 1 month?
- 3 months?
- 6 months?
- Or zero?
Here’s the shocking statistic: 73% of Americans live paycheck to paycheck. That means 3 out of 4 people are just one missed paycheck away from financial disaster.
In 2024, the average American household debt reached $17,000 in credit card debt alone. Add student loans ($37,000 average), car loans, and mortgages, and the average working professional is drowning in over $100,000 of debt by age 30.
But here’s the part nobody tells you:
It’s NOT your fault. You weren’t taught money management in school. You were taught to:
- Get a “safe” job
- Work 40+ hours a week
- Buy a house you can barely afford
- Finance a car you don’t need
- Retire at 65 (if you’re lucky)
That system is broken. And in 2026, it’s crumbling faster than ever.
In this post, I’m going to show you:
- Why the traditional “American Dream” is a trap
- The exact formula to build wealth from zero
- How to escape the 9-to-5 rat race
- 5 income streams you can start today (for under $100)
- Real examples of people who did it
Let’s destroy the myth and build real wealth.
Part 1: Why the Traditional Path is a Trap
🏢 The “Safe Job” Illusion
Growing up, you were probably told: “Study hard, get good grades, find a stable job, and you’ll be fine.”
But let’s look at the reality:
| Year | Average Salary | Average Home Price | College Tuition |
|---|---|---|---|
| 1980 | $21,000 | $47,000 | $9,000/year |
| 2024 | $65,000 | $420,000 | $38,000/year |
Inflation has outpaced wages by over 400%. You’re working harder than your parents did, but you’re getting less. The math simply doesn’t work anymore.
💳 The Debt Spiral
Here’s how the average American ends up broke:
- Get a student loan ($37,000)
- Get a car loan ($35,000)
- Get a mortgage ($300,000+)
- Use credit cards for daily expenses (18-25% APR)
- Work 40 years to pay it all off
Result: You’re a “high earner” but a “low net worth” individual. You look rich on Instagram, but you’re one emergency away from bankruptcy.
Part 2: The $100,000 Rule – The Math That Changes Everything
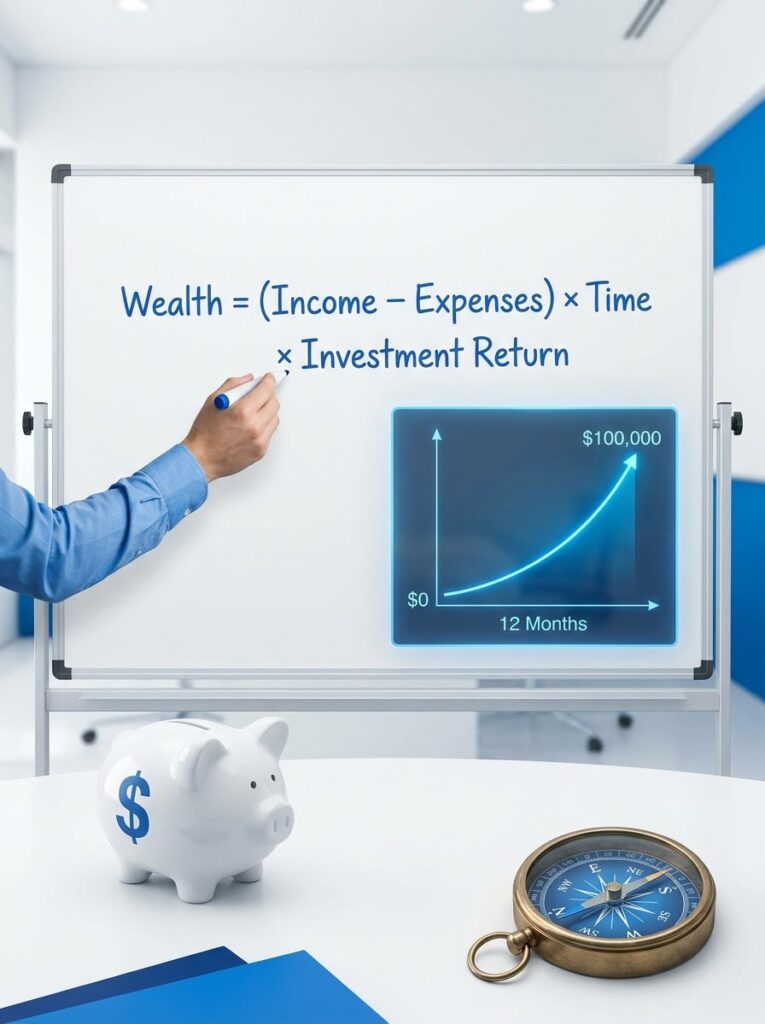
Here’s the formula I want you to memorize:
Wealth = (Income – Expenses) × Time × Investment Return
That’s it. Four variables. Four levers you can pull.
🔑 Variable 1: Increase Your Income
The average American earns $65,000/year. But if you can increase that to $100,000/year (just a 53% increase), here’s what happens:
| Income | Monthly Savings (20%) | 10-Year Wealth (8% Return) |
|---|---|---|
| $65,000 | $1,083 | $198,000 |
| $100,000 | $1,667 | $305,000 |
| $150,000 | $2,500 | $458,000 |
The difference is $107,000 in 10 years. That’s a down payment on a house. That’s early retirement. That’s freedom.
🔑 Variable 2: Cut Expenses (Without Sacrificing Happiness)
You don’t need to live like a monk. But here are 3 things you can cut TODAY:
- Cancel unused subscriptions (average American spends $219/month on subscriptions they don’t use)
- Cook at home 3 more days a week (saves $200+/month)
- Refinance high-interest debt (saves thousands in interest)
🔑 Variable 3: Invest Early (The Power of Compound Interest)
This is the magic formula that rich people know and poor people ignore.
If you invest $500/month from age 25 to 65 at 8% annual return → $1.8 million
If you start at age 35 instead → $743,000
That 10-year delay costs you over $1 million. Start TODAY. Not tomorrow. Not next year.
Part 3: 5 Income Streams You Can Start in 2026 (Under $100)
The wealthy don’t have one job. They have multiple income streams. Here are 5 you can start right now:
💻 1. Freelancing on Upwork / Fiverr
- Cost to start: $0
- Potential income: $500–$5,000/month
- Skills in demand: Copywriting, graphic design, web development, virtual assistance
- Action: Create a profile TODAY. Send 5 proposals. Land your first client.
📦 2. Amazon FBA (Sell Physical Products)
- Cost to start: $50–$100 (for samples + listing)
- Potential income: $1,000–$20,000+/month
- How: Find a trending product on Jungle Scout, order samples from Alibaba, list on Amazon, run ads.
- Action: Watch 3 YouTube videos on Amazon FBA tonight.
📝 3. Affiliate Marketing (Promote Products)
- Cost to start: $0
- Potential income: $500–$10,000+/month
- How: Join Amazon Associates or ShareASale. Promote products on social media, blogs, or YouTube.
- Action: Create a niche Instagram page (e.g., “TechUnder100”) and post daily.
🎓 4. Digital Products (E-books / Courses / Templates)
- Cost to start: $0 (use Canva + Gumroad)
- Potential income: $1,000–$50,000+/month
- How: Identify a problem → Create a PDF solution → Price it at $10–$50 → Sell on Gumroad.
- Action: Write a 20-page e-book this weekend. Sell it by Monday.
🎥 5. YouTube Automation (Faceless Channel)
- Cost to start: $0 (use AI tools for voiceover + editing)
- Potential income: $500–$10,000+/month
- How: Create content on trending topics (finance, motivation, tech) using stock footage + AI voice.
- Action: Upload 1 video per week for 3 months.
Part 4: Real Stories – People Who Escaped the Rat Race
📍 Sarah from Texas – From Teacher to $12,000/month
Sarah was a school teacher earning $48,000/year. She started a side hustle selling printables on Etsy. Within 18 months, her Etsy store was generating $12,000/month. She quit teaching and now works 10 hours/week.
📍 Mike from New York – From $60k to $200k in 2 Years
Mike was a marketing manager. He started freelancing on Upwork as a copywriter. Within 6 months, he was earning $5,000/month on top of his salary. Within 2 years, he quit his job and now runs a copywriting agency.
📍 Aisha from London – From $0 to $50,000 in 1 Year
Aisha had no savings and no degree. She started an Amazon FBA store with $100. Her first product failed. Her second product broke even. Her third product made $5,000 profit in the first month. She now sells 5 products and earns $50,000+/month.
Part 5: The Step-by-Step 12-Month Wealth Plan
Month 1-3: Build Your Foundation
- Track every dollar you spend (use Mint or YNAB)
- Cut $200/month in expenses
- Build a $1,000 emergency fund
- Start ONE side hustle from the list above
Month 4-6: Grow Your Income
- Increase your side income to $1,000/month
- Invest $500/month in an S&P 500 index fund (VOO or SPY)
- Read 5 books on personal finance (start with Rich Dad Poor Dad and The Simple Path to Wealth)
Month 7-9: Scale Your Investments
- Increase side income to $2,500/month
- Max out your Roth IRA (or 401k if available)
- Start investing in real estate (REITs or a rental property)
Month 10-12: Achieve Financial Freedom
- Reduce your expenses to 50% of your income
- Reach $100,000 net worth milestone
- Plan your retirement date (target: 50% earlier than the traditional 65)
❌ 5 Mistakes That Keep People Broke
1. Lifestyle Inflation
“You get a raise, you buy a nicer car.” This is a trap. Keep your lifestyle the same and invest the difference.
2. Bad Debt (Credit Cards at 25% APR)
If you have credit card debt, pay it off BEFORE investing. That 25% interest is killing your wealth faster than any investment can grow.
3. Not Investing Early
Time is the most valuable asset. Waiting 5 years costs you millions.
4. Trying to Get Rich Quick
There are no shortcuts. Anyone selling a “get rich quick” course is getting rich off YOU. Real wealth takes time and patience.
5. Not Having a Plan
“If you fail to plan, you plan to fail.” Write down your goals. Track your progress. Adjust when needed.
🎯 A Quote to Remember
“The rich invest in time. The poor invest in money. The middle class invest in things.” – Warren Buffett
Final Thoughts: Your 2026 is a Choice
Here’s the reality:
The average person will stay in their comfort zone, scroll social media, complain about inflation, and work until they’re 65—exhausted, stressed, and barely surviving.
The top 1% will read this, take action, build multiple income streams, invest early, and retire at 45—living life on their own terms.
Which one are you going to be?
The tools are all here. The roadmap is clear. The only missing piece is YOU.
Don’t wait for next year. Don’t wait for “the right moment.” The right moment is NOW.
Get started. Take action. And in 12 months, look back and thank yourself for making the decision to change your life.